Category

Finance

Category

Most investors in India think about taxation only when the financial year ends and they need to file their income tax returns. By that point, the tax liability is already crystallised, and there is little that can be done to reduce it other than making hasty investments in tax-saving instruments. The investors who consistently minimise their tax burden on market gains are those who integrate tax planning into their investment decision-making from the very beginning – considering the tax implications of each transaction before executing it rather than after. This discipline begins with understanding how the regulatory framework governing trading apps and the securities held in a demat account treats different types of investment activity for tax purposes.

Short-Term Versus Long-Term Capital Gains: The Core Distinction

The holding period of an investment determines whether the gains will be clubbed under the short-term or long-term category, which has a direct bearing on the taxation. Listed equity shares and equity-oriented mutual fund units held for less than twelve months are taxed as short-term capital assets and taxed at twenty per cent. However, equity shares and equity-oriented mutual fund units held for more than twelve months are taxed as long-term capital assets. Long-term capital gains arising out of transfers of these assets are taxed at twelve and a half per cent beyond one lakh twenty-five thousand in a financial year with no indexation benefit.

The implication of this is simple. If you sell a winning equity stock a day before completing one year of holding, you will be taxed at a significantly higher rate than if you hold it beyond one year. Even for big gains, this difference in tax rates could be worth a large sum of money. Keeping a tab on how long you have held on to a particular winning stock and considering it while making exit decisions is a basic aspect of portfolio management that all serious investors would consider.

Tax Loss Harvesting: Way To Use Losses To Offset Gains

Tax-loss harvesting is a process wherein you book losses on your investments and use them to offset gains in your portfolio. Capital losses arising out of equity-oriented investments could be set-off against capital gains of similar assets. Short-term capital losses could be set-off against short-term capital gains and long-term capital losses could be set-off against long-term capital gains. Further, unadjusted capital losses could be carried forward for a maximum of eight assessment years to offset future gains.

To do tax-loss harvesting, you will need to look out for scrips in your portfolio that have suffered losses. You will need to evaluate whether the scrips still hold value for you. If they do, you could sell them to adjust your losses and re-buy them after thirty trading days. The timing of tax-loss harvesting is also important since you need to complete the process before the end of the financial year, i.e., before March 31.

While tax-loss harvesting does not directly add to your returns, it enables you to retain more of your returns in your pocket, which is similar to earning additional returns. These additional returns in your portfolio compound over time and enhance your overall returns.

Business Income Vs Capital Gain: What Differs?

As you engage more and more in trading activities, there could come a time when the Income Tax Department views your activity as business income rather than capital gain. The implications of it could be significant. First, you might end up paying taxes at a higher rate. Second, you will not be able to set-off losses against income from other sources.

However, you will also be able to reclaim some of your expenses that you were not able to claim as deductions earlier. Expenses like brokerage commission, internet charges, subscription fees for stock-related software, and even home office depreciation could be claimed as deductions to arrive at the net business income.

There is no bright-line test to determine whether you are an investor or a trader. Factors like the number of trades executed, the quantum of risk taken, the period for which the position is held, and whether the derivatives are used for hedging also determine whether you will be taxed as an investor or a trader. If you are confused whether you fall in the category of an investor or a trader, it is best to consult a CA specialising in capital market taxation since the tax implications could be significant. Inadvertent misclassification could also invite notices from the tax authorities with interest and penalties, which could be far greater than any tax savings that you anticipated.

ITR Filing And Reconciliation With Broker Reports

Filing tax returns for equity investors is one of the most crucial activities of the year. The process involves reconciling the tax profit and loss statement that your broker provides with the Annual Information Statement available on the Income Tax Department’s website and the TDS (Form 26AS) that shows how much tax has been deducted by the broker. The discrepancy between various statements is quite common, which is why some investors get notices from the Income Tax Department. Most brokers provide a detailed tax-wise profit and loss statement that breaks down the gains and losses according to the holding period and calculates short-term and long-term gains separately. These statements can become a basis for filing tax returns for investors.

If you have invested in offshore platforms or international fund-of-funds schemes, you will need to file additional documents regarding foreign assets, which are mentioned under Schedule FA of ITR forms. Failure to report foreign assets might lead to heavy penalties. Tax filing is not something that you should attempt on your own if you are an active equity investor with multiple income sources. It is always better to get help from professionals to ensure you get every tax deduction that you are eligible for and claim all the benefits that you are entitled to, which might save you more money in the long run.
You may already be doing what most people do with retirement money. You save, you glance at statements, you hope the numbers are moving in the right direction, and then a letter shows up about taxes, distributions, or plan rules and your stomach drops a little. Pension and retirement funds carry a strange mix of comfort and pressure, which is why many people turn to CPA tax planning services in Holladay UT. They are supposed to create security, yet one missed rule or one bad decision can make the whole thing feel fragile.

That is where a Certified Public Accountant can help. Retirement accounts are not just savings buckets. They come with tax rules, timing rules, beneficiary issues, employer plan limits, and distribution requirements that change as your life changes. How CPAs assist in managing pension and retirement funds often comes down to one thing. They help you keep more of what you saved by reducing avoidable tax costs, catching compliance problems early, and turning a confusing plan into a clear one.

Retirement fund management gets harder when life stops being simple

Retirement planning looks clean on paper. Contribute while you work. Invest with care. Withdraw later. Real life does not stay that neat. A job change can leave you with old 401(k) accounts in different places. A spouse can retire earlier than expected. A pension election can lock in a choice you cannot reverse. If you inherit an IRA or start taking income at the wrong time, the tax hit can be larger than you expected.

That pressure grows when retirement is close. You are no longer deciding only how much to save. You are deciding how to turn accounts into income without creating tax trouble. You might need to coordinate Social Security, pension payouts, IRA withdrawals, and taxable investment income in the same year. One move affects the next.

A CPA helps sort those moving parts into a sequence that makes sense. That can include reviewing contribution limits, tracking cost basis, estimating annual tax liability, and planning withdrawals so you do not accidentally push yourself into a higher tax bracket. This is the practical side of retirement fund management. It is not only about investment returns. It is about what actually reaches your bank account after taxes and penalties.

Tax mistakes can drain pension and retirement savings quietly

Many retirement mistakes do not look dramatic at first. They look small, even harmless. You forget an old account. You miss a required distribution. You roll money into the wrong account type. You take a lump sum from a pension without understanding the tax result. The damage often shows up later, when there is less time to recover.

The IRS has clear rules on required minimum distributions, and those rules matter once you reach the age when withdrawals must begin from certain retirement accounts. A CPA can calculate the amount, confirm which accounts are affected, and help you avoid penalties tied to missed or incorrect distributions.

Pension plans bring their own concerns. If you are part of an employer sponsored retirement plan, reporting and fiduciary standards also matter. The U.S. Department of Labor outlines key rules for retirement plans under ERISA in its retirement plan guidance. For business owners and plan sponsors, a CPA often helps with filings, plan operations, and record accuracy so the plan stays compliant.

This is also where emotions show up. People freeze because they do not want to make the wrong move. They delay paperwork, avoid opening notices, or keep telling themselves they will deal with it next month. A good CPA gives structure to that fog. Not pressure. Structure.

Longer lives make retirement income planning more demanding

Retirement money now has to work longer than many people expected. That changes everything. A pension election that seemed fine at age 62 may look thin at 82. Withdrawals that feel manageable in the first five years of retirement can become risky if health costs rise or markets fall.

Research from the Stanford Center on Longevity points to a growing need for stronger financial security planning for longer lives. That is one reason a CPA’s work matters beyond tax season. They can help model withdrawal patterns, estimate future tax exposure, and coordinate income sources so your plan is built for duration, not just the next year.

DIY retirement oversight and professional CPA support create different outcomes

Area Handling It Yourself Working With a CPA
Required distributions Higher chance of missed deadlines or incorrect amounts Amounts and timing are reviewed against current IRS rules
Pension payout choices May rely on guesswork or a single benefits packet Tax impact and long term income tradeoffs are compared
Multiple retirement accounts Old plans may be overlooked or poorly coordinated Accounts are organized into one withdrawal and tax strategy
Annual tax planning Often reactive after the year ends Withdrawals and income are planned before tax problems grow
Plan compliance for employers Errors may go unnoticed until an audit or complaint pension and retirement fund management includes reporting support and record review

Three steps can bring retirement accounts back under control

Gather every account and plan document. Pull statements for pensions, IRAs, 401(k)s, 403(b)s, inherited accounts, and annuities. Include beneficiary forms if you have them. Most confusion starts because the full picture is missing.

Map out the next three years of withdrawals. Do not focus only on this month. Estimate when income will start, which accounts you plan to tap first, and whether required distributions are approaching. This simple forecast often reveals tax issues before they become expensive.

Ask for a retirement tax review from a CPA. A certified public accountant can review distribution timing, rollover decisions, pension options, and reporting obligations. That kind of review is often where hidden risks finally become visible.

Clear retirement planning starts with the right support

You do not need to know every pension rule or memorize every retirement account deadline. You do need a plan that fits your life, your taxes, and the years ahead. When retirement funds are handled with care, they stop feeling like a pile of separate accounts and start working like income with a purpose.

If your retirement picture feels scattered, a Certified Public Accountant can help you organize it, protect it, and make smarter decisions with it.

Why Gold Loans Are Popular in India

Gold loans have become India’s preferred short-term credit solution, with RBI data showing outstanding amounts exceeding ₹1.1 lakh crore in FY2024. Unlike traditional loans, gold loan eligibility criteria are refreshingly simple, making credit accessible to millions who might struggle with conventional lending requirements. 

Whether you’re a housewife, a retired professional, or someone with fluctuating income, understanding these eligibility parameters can unlock instant liquidity.

Essential Age and Residency Requirements

The foundation of gold loan eligibility starts with basic demographic criteria that most lenders follow consistently. You must be between 21 and 70 years old at most financial institutions, though some banks like ICICI extend the upper limit to 85 years. This broad age range means everyone from young professionals starting their careers to senior citizens can access gold-backed credit.

Indian residency is mandatory for gold loan eligibility. NRIs cannot apply for standard retail gold loans, as lenders require local address verification and physical gold assessment. Your residency proof becomes part of the KYC documentation that streamlines the approval process.

Consider this scenario: A 68-year-old pensioner in Mumbai wants to fund his grandson’s medical treatment. Despite having no regular income beyond his pension, his 40 grams of 22-karat gold jewellery make him fully eligible for a substantial loan amount.

Gold Ownership and Type Requirements

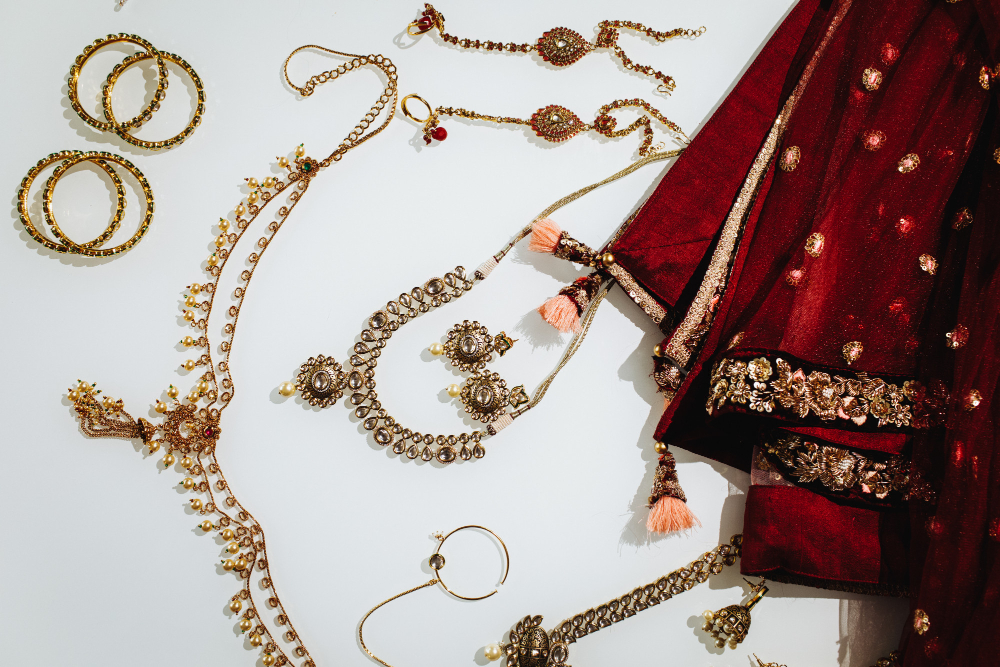
Traditional gold Indian wedding jewellery.

Your gold loan eligibility hinges on owning acceptable gold assets. Lenders exclusively accept gold jewellery like chains, bangles, rings, and earrings. Gold coins, bars, biscuits, or utensils don’t qualify for personal gold loans, regardless of their purity or value.

The gold must belong to you or your immediate family members. Joint ownership within the household is acceptable, but you cannot pledge borrowed or rented gold items. This ownership verification happens during the application process when lenders document the gold’s source and your relationship to it.

Purity and weight standards:

  • Minimum purity: 18 karat (75% gold content)
  • Maximum accepted: 22 karat (91.6% gold content)
  • Typical minimum weight: 10 grams per ornament
  • Some premium lenders require 22-karat minimum
Pro Tip: Only gold jewellery qualifies for most gold loans. Coins, bars, and utensils are typically excluded from standard lending products.

Documentation and KYC Compliance

Gold loan eligibility requires minimal paperwork compared to other credit products. You need basic KYC documents that most Indians already possess, making the process remarkably straightforward.

Required documents:

  • Identity proof: Aadhaar, PAN, Voter ID, Passport, or Driving Licence
  • Address proof: Same as identity documents or utility bills
  • PAN card (mandatory only for loans above ₹5 lakh)
  • Passport-size photographs

The beauty of gold loan eligibility lies in what you don’t need. No income certificates, salary slips, ITR documents, or business turnover statements are required. This makes gold loans accessible to housewives, students, and anyone with irregular income patterns.

Did You Know?: Gold loans don’t require minimum CIBIL scores. Even borrowers with poor credit history can qualify based solely on their gold’s value and purity.

Income and Employment Flexibility

Gold loan eligibility transcends traditional employment categories, making it genuinely inclusive. Whether you’re salaried, self-employed, or unemployed, your eligibility depends on gold ownership rather than income stability.

Eligible borrower categories:

  • Salaried professionals (any income level)
  • Self-employed individuals and business owners
  • Housewives and homemakers
  • Pensioners and retirees
  • Students (above minimum age)
  • Freelancers and gig workers

The interest on gold loans remains competitive regardless of your employment status, as the physical collateral eliminates lenders’ income-related risks.

Special Considerations and Restrictions

While gold loan eligibility is broadly inclusive, certain restrictions ensure responsible lending practices. You cannot use loan proceeds to purchase more gold, as RBI guidelines prohibit gold-for-gold lending cycles.

Geographic accessibility varies, with urban and semi-urban areas having better gold loan eligibility infrastructure. Digital lenders now offer doorstep services, expanding access to previously underserved locations.

The process typically involves gold assessment, purity testing, weight verification, and immediate loan approval. Most lenders complete this within hours, making gold loans ideal for emergency funding needs.

In a Nutshell

Gold loan eligibility offers unmatched accessibility in India’s credit landscape. With minimal documentation, no income requirements, and asset-backed security, these loans serve diverse financial needs across economic segments. 

The combination of competitive interest rates, flexible repayment options, and quick processing makes gold loans an optimal choice. If you meet the basic age and residency criteria and possess gold, you’re likely eligible for immediate credit access.

FAQs

1. What gold loan eligibility criteria apply to housewives without income?

Housewives can easily qualify for gold loans without income proof. Only gold ownership, age compliance, and basic KYC documents are required for approval.

2. Does a poor CIBIL score affect gold loan eligibility for borrowers?

No, CIBIL scores don’t impact gold loan eligibility. Asset-backed lending focuses on gold value and purity rather than credit history or scores.

3. What minimum gold purity standards determine gold loan eligibility in India?

Most lenders accept 18–22 karat gold jewellery for eligibility. Some premium institutions require a minimum of 22-karat purity for optimal loan terms and processing.

4. Can senior citizens above 70 years meet the gold loan eligibility requirements?

Age limits vary by lender, with most capping at 70 years. However, banks like ICICI extend gold loan eligibility up to 85 years.

5. How does interest on gold loans vary based on borrower eligibility categories?

Interest on gold loans remains consistent across borrower types since physical collateral eliminates income-related risks. Rates depend on loan amount and tenure rather than eligibility category.

References

  1. https://www.rbi.org.in/Scripts/BS_PressReleaseDisplay.aspx?prid=54321
  2. https://www.bajajfinserv.in/gold-loan-eligibility-and-documents
  3. https://sbi.co.in/web/personal-banking/loans/gold-loan/personal-gold-loans
  4. https://www.icicibank.com/personal-banking/loans/gold-loan
  5. https://www.hdfcbank.com/personal/borrow/loan-against-assets/gold-loan

I woke up one morning to find my social feed inundated with Dogecoin memes once more – a swarm of Shiba Inus, rockets, and “To the moon!” posts. And there it was. Not interest in the doge coin itself so much as how to invest in the currency, but joining in an online culture that has gained rang beyond a mere joke. If you’ve ever wanted to know how to jump on board safely without getting lost in all the noise, this is going to be pretty informative for you. In fact if you have some clue as to where to begin and what to be wary of, purchasing DOGE can really be quite easy and fun.

Looking for a safe spot to kick off your Dogecoin adventure

The very first step of finding out how to buy doge is to figure where to do it. Consider this akin to choosing the café you would chill at- some have a good vibe, some are just loud and unpredictable. The current crop of crypto exchanges falls along the same lines. Established platforms such as Bitget streamline the buying of Dogecoin in a process rather friendly for beginners while maintaining safety.

Before you dive in, confirm that your selected exchange is licensed or regulated in your country. This is much more significant than most people realize. A legitimate exchange safeguards your funds, encrypts data for security, and recovery in case something goes wrong. If the site looks dodgy, has bad support, or ludicrous promises, that’s your cue to step back.

To buy Doge the first lesson is to choose your playground. An excellent platform equals peace of mind before you even hit the click “buy”.

Every proper exchange will ask you to verify your identity. Kind of boring, I know, but it’s just one of the things when buying doge safely. It usually entails uploading an ID card or passport, and sometimes a selfie to make sure you’re really who you say you are.

We’re not doing it to bug you. We need to keep our platform and its users safe from fraud and bots. Most importantly, after verification, your account will have much higher transaction limits, increased withdrawals, and complete security features. Take this part seriously. Do not share the verification info anywhere other than the platform’s official site.

By the time you finish setting up your account, you’ll already be one step closer to understanding how to buy doge like a pro.

More funds without breaking into a sweat

Once fully identified, the account has to be filled. Most exchanges do make this simple by availing themselves of several ways in which one can deposit money, be it bank transfers and debit cards or third-party services. Note transaction fees while learning how to buy doge, that’s one way in which the investment can creep up quite silently and significantly.

Credit card deposits are usually fast but come at a slightly higher cost. Bank transfers, in contrast, are slow but inexpensive. If you have some crypto already, you can deposit in USDT or USDC and then exchange that for Dogecoin.

Small yet vital: begin with little. Test your first deposit to see if the payment route works. Such a minor practice can save you much anxiety later in transferring big sums.

First Dogecoin purchase

And here it is, quite interesting — “how to buy doge” in real “how to buy doge” moment. Once your funds are in your trading platform, go to the exchange section. Look for DOGE and more often you would see a pair such as DOGE/USDT or DOGE/USD. Pick how much you wish to purchase, input the information again and double-check all the details, and then click on confirm.

As a means of taking charge of the price at which you are purchasing, it is preferable to use a “limit order” as opposed to a “market order.” This would allow you to fix the designated price at which you intend buying the DOGE. Once that is reached in the market, your order goes through automatically.

Soon after some seconds or minutes, the DOGE that you have bought is going to reflect in your spot wallet. Congratulations — you just learned how to buy doge in a safe way without overcomplicating the process.

After you buy your DOGE, the very next step to take is keeping it safe. This is a very important part of learning how to buy doge responsibly: securely storing your crypto. Leaving your coins on an exchange isn’t too bright, especially if you are planning on holding onto them long term.

Generally, we have two main storage options: hot wallets and cold wallets. Hot wallets are online and hence much more convenient to use but are often susceptible to hacking. Cold wallets, such as Ledger or Trezor hardware devices, keep the assets offline and away from such online-based vulnerabilities.

The Correct and the Wrong Ways

Of course, some put coins into a wallet just to leave them there and do not think about the future of a particular currency. For such people, it might not be essential to understand timing and market behavior to draw profit from trading. Not Sure How to Use My Wallet When It Comes to Active Trading

Everybody would like to buy at the bottom and sell at the top. That’s easier said than done. Timing is a huge part of the equation regarding your success with crypto. So while you learn how to buy doge, bear in mind that market timing is not a matter of guesswork, it is a matter of patience.

The price of Dogecoin can be highly volatile and reactive to news, social media hypes, or just broader trends in all of crypto. Staying cool, like dollar-cost averaging (buying small amounts over time), helps reduce risk. You’re not going to get the lowest price every time, but you will average it out.

Being patient is a part of investing with confidence. The aim isn’t only to know how to buy doge but to understand what to do with it once you have it.

You should be security conscious always as a Dogecoin owner

Holding DOGE means taking the security of your investment into your hands. This exceeds prudent storage of the coins alone, it touches on your general digital hygiene. Require 2FA to be used on any exchange or wallet login. Refrain from using public Wi-Fi when accessing your cryptocurrency accounts. Always log out following a trade.

The other important thing is to know how to buy doge safely from being scammed. In case someone promises to double your DOGE, or ask for your wallet seed phrase, then this is a scam. Exchanges never ask for their clients’ private keys. Have the official website bookmarked and don’t click on links in unsolicited messages or fake social media profiles. Keeping these habits up will keep you safe well beyond your initial investment.

Plan Your Investment

Before hitting the “buy” button again, just stop and think about your game plan. It’s not just being able to buy doge that matters, it’s knowing when and why you want to hold it and for how long.

Are you in to scoop short-term gains and sell or are you in because you believe in its potential for the long run? These are both valid but require different mindsets. Long-term holders usually move coins to secure wallets and do not care much about prices on a daily basis. Traders, on the other hand, watch charts and news every day.

Sell or swap your Dogecoin

If you’ve set goals in Dogecoin, you’ll have a foundation when the prices drop. When DOGE goes through that ‘dip,’ you’ll know it’s part of your strategy – not your bad judgment. This is the emotional distance that distinguishes an impulsive ‘buyer’ from a confident investor.

Eventually, you may want to cash out or trade DOGE for another asset. Knowing how to buy doge also means understanding how to sell it safely. You can sell it back to fiat on your exchange or trade it for another cryptocurrency, such as Bitcoin or Ethereum.

Before confirming a sell order, make sure to confirm the current price at which the asset is trading, the charges involved, and respective withdrawal modes available. Before converting the same to fiat, confirm from your bank if they allow receipts in terms of cryptocurrency. Some regions demand further confirmation before withdrawing from a cryptocurrency to fiat. Better plan for these needs ahead of time.

In case you are swapping, take a second look to make sure you have selected the correct trading pair. When these steps become a part of your workflow, the entire activity will feel effortless and assured.

Long run smartness

A healthy habit of crypto necessitates buying DOGE more than once. Updating your apps and information would keep you following the official community channel regularly and never communicating private information.

The more you are familiar with how to buy doge and keep it, the less it will be about speculation and a lot more about discipline. Behind meme roots, Dogecoin has a passionate community and an ever-growing ecosystem. It is the energy that keeps the coin alive, bringing investors back year after year.

Final thoughts

Purchasing doge securely isn’t something that should be reserved for tech wizards or even day traders. This should just mean being careful and educated. Just don’t be afraid to take that first step and open your wallet. Just start with an exchange you can be sure of, like Bitget, and take it little by little in terms of investment, store it safely, and build good practices in preserving your assets.

You don’t have to chase every price swing or follow every hype wave. True confidence comes from the realization that you are doing the best you can with your investments. And once you learn how to buy doge in the right manner, you will find that cryptocurrencies are not as scary as they seem at first, just one more frontier for an inquiring and responsible explorer.

Wealth management firms specializing in Bitcoin have developed sophisticated client acquisition strategies distinctly different from traditional financial advisors and retail cryptocurrency platforms. These specialized firms target ultra-high-net-worth individuals through carefully crafted approaches addressing the unique concerns of sophisticated investors considering digital asset allocation. The methods reflect a fundamental evolution beyond early cryptocurrency adoption strategies, creating service models specifically designed for clients with complex wealth preservation requirements and institutional-grade expectations.

The client acquisition process begins long before direct outreach through strategic positioning within established wealth networks. According to financial industry research analyzing Bitcoin advisory services, relationship development through existing professional connections represents the primary successful pathway. This Source uncovers that 78% of new high-net-worth clients come from trusted advisor recommendations rather than marketing campaigns.

Credibility formation pathways

  • Traditional credential leveraging – Bitcoin wealth managers strategically emphasize conventional financial credentials alongside cryptocurrency expertise when targeting sophisticated clients. Firms successfully attracting high-net-worth individuals typically showcase advanced traditional designations, including CFAs, CPAs, and similar established credentials, before highlighting Bitcoin specialisation, creating familiarity bridges between conventional wealth management and digital asset advisory services.
  • Multi-generational household targeting – Strategic focus on next-generation family members within existing wealthy households creates unique access pathways impossible through direct principal targeting. Bitcoin advisory firms report 40% higher client acquisition success when engaging adult children within wealthy families rather than approaching wealth principals directly, particularly when family office structures control substantial multi-generational assets.
  • Privacy-centric service architecture – Purpose-built confidentiality frameworks addressing cryptocurrency transaction visibility concerns represent critical differentiation for wealth managers targeting privacy-conscious clients. Sophisticated service models implementing specialised reporting structures, enhanced asset segregation, and discrete transaction pathways demonstrate particular effectiveness with privacy-prioritising high-net-worth segments typically sceptical of standard cryptocurrency platforms.

Technical differentiation markers

Advanced Bitcoin wealth managers implement several specialized service components, creating meaningful separation from both traditional advisors and standard cryptocurrency platforms:

  • Custom multi-signature implementation tailored to family governance structures rather than standardized security models, particularly aligning authorization thresholds with existing estate planning frameworks.
  • Specialized tax efficiency strategies leveraging sophisticated Bitcoin-specific approaches unavailable through general tax advisors, including strategic jurisdiction selection, basis calculation optimization, and long-term philanthropic planning integrating digital assets.
  • Institutional custody relationships provide preferential access thresholds, dedicated account representatives, and customised reporting systems typically unavailable below $ 50 M+ investment levels despite substantially lower client portfolio allocations.
  • Private market access leveraging wealth manager relationships, securing participation rights in early-stage Bitcoin infrastructure investments, mining operations, and venture opportunities unavailable through conventional investment channels.

Psychological barrier removal

Successful Bitcoin wealth managers directly address specific psychological barriers preventing high-net-worth adoption through specialized approaches:

  • Comprehensive “investment thesis” frameworks providing sophisticated justification narratives satisfying wealth preservation mandates beyond speculation motives. These structured allocation rationales emphasize portfolio effect contributions, inflationary hedge characteristics, and intergenerational wealth transfer advantages rather than growth potential alone.
  • Established advisory board relationships featuring recognised financial authorities, creating credibility impossible through internal expertise alone. These strategic associations provide essential legitimacy signals, particularly effective with traditional wealth segments requiring established validation before considering novel asset classes.
  • Continuous education systems providing discreet, client-appropriate knowledge development rather than technical cryptocurrency training are inappropriate for sophisticated financial clients. These educational approaches emphasise contextual understanding within existing financial frameworks rather than standalone Bitcoin knowledge, typically targeting retail participants.

Bitcoin wealth management continues evolving distinct service models addressing sophisticated investors’ specific requirements beyond traditional financial services and cryptocurrency-native platforms targeting retail participants.

Understanding the Solvency Ratio

When it comes to protecting your family’s financial future, choosing the right life insurance policy is a pivotal decision. Among various factors to consider, the solvency ratio of an insurance provider emerges as a crucial indicator of its financial health and reliability. This article delves into the significance of the solvency ratio and how it ensures the security of your term insurance policy.

What is Solvency Ratio?

The solvency ratio is a key metric that measures the financial stability of an insurance company. It is calculated as the Available Solvency Margin (ASM) over the Required Solvency Margin (RSM), showcasing the company’s ability to meet its long-term obligations. The Insurance Regulatory and Development Authority of India (IRDAI) mandates a minimum solvency ratio of 150%, ensuring that insurers maintain a buffer to secure policyholders’ interests.

Why Solvency Ratio Matters

  1. Indicator of Financial Health: A robust solvency ratio is indicative of an insurer’s financial strength, signalling its capability to withstand financial stress and honour claims. It acts as a beacon for potential policyholders, guiding them towards insurers who are more likely to be solvent and operational in the long term. Furthermore, a strong solvency ratio can contribute to the insurer’s overall market reputation, attracting more customers and potentially leading to better terms for policyholders.
  2. Assurance of Claim Settlement: High solvency ratios reassure policyholders about the insurer’s ability to fulfil its promise of claim payments, ensuring that your loved ones are not left in a financial lurch. This assurance is particularly critical in times of economic downturns or when unforeseen events increase the number of claims. Additionally, it fosters a sense of trust and reliability between the insurer and the policyholder, which is fundamental in the insurance relationship.
  3. Reflects Risk Management: It reflects the insurer’s prudence in managing risks, maintaining a balance between its assets and liabilities. This balance is essential not only for the insurer’s long-term viability but also for the financial ecosystem’s stability, as it prevents cascading failures that could affect the broader market. Effective risk management, as indicated by a healthy solvency ratio, also implies that the insurer is well-prepared for unforeseen events, ensuring continuity and reliability of service to policyholders.

Calculating the Solvency Ratio

The solvency ratio is calculated by dividing the net income and depreciation by the company’s total liabilities. This formula assesses the insurer’s cash flow relative to its obligations, providing insight into its financial sustainability.

The Importance of a High Solvency Ratio

  • Stability and Reliability: Companies with higher solvency ratios are deemed more stable and reliable, which is crucial for policyholders relying on the insurer for future claim settlements. This stability ensures that in times of economic downturns or unexpected financial challenges, the insurer remains well-equipped to honour its commitments. Additionally, a stable financial foundation fosters trust among policyholders, contributing to a stronger relationship between the insurer and its customers.
  • Regulatory Compliance: Adhering to IRDAI’s solvency ratio requirements is not just about compliance; it’s a testament to the insurer’s commitment to safeguarding policyholder interests. It also reflects the company’s ability to efficiently manage its resources and liabilities, ensuring long-term operational sustainability. Compliance with these regulations not only protects the policyholders but also contributes to the overall health of the financial system, promoting a more secure insurance marketplace for everyone involved.

How to Assess an Insurer’s Solvency Ratio

Evaluating an insurance company’s solvency ratio involves reviewing its financial statements and regulatory filings. This information, often available on the IRDAI website or the insurer’s investor relations page, provides a snapshot of its financial health.

The Utility of a Term Insurance Calculator

In the journey of securing a term insurance policy, understanding the premium and coverage is paramount. This is where a term insurance calculator becomes an invaluable tool. It simplifies the process of estimating your insurance needs, factoring in your age, income, financial obligations, and the desired coverage amount. By inputting these variables, the calculator presents you with an estimated premium, helping you make an informed decision tailored to your financial situation and goals.

Term Insurance Benefits: A Snapshot

Term insurance stands out as a fundamental safety net, offering a straightforward promise: financial security for your loved ones in your absence. Term insurance benefits are concise yet profound:

  1. Affordable Premiums: Term insurance is known for its cost-effectiveness, allowing policyholders to secure substantial coverage at relatively low premiums.
  2. Simplicity: With clear terms and conditions, it’s easy to understand, ensuring you know exactly what you’re getting.
  3. Flexibility: Many term plans offer riders for additional protection against critical illness, disability, etc., tailoring coverage to your unique needs.
  4. Tax Benefits: Tax benefits can be availed under sections 80c and 10d.

Conclusion

The solvency ratio is more than a financial metric; it’s a protective shield for your term insurance policy. It ensures that the insurer you trust to secure your family’s future is capable of standing by its commitments, even in challenging times. When selecting an insurance provider, a high solvency ratio should be a key consideration, offering peace of mind that your loved ones will be supported, no matter what the future holds.

The financial landscape is continuously evolving, and Denver’s credit unions are at the forefront of this change, offering innovative solutions to meet the diverse needs of their members. Known for their member-focused approach, credit union Denver are redefining the banking experience with a range of services tailored to modern financial demands. This article delves into how these credit unions are revolutionizing the financial sector with their unique offerings.

Understanding Credit Unions in Denver

What Sets Them Apart

Credit unions are member-owned financial institutions that typically offer lower fees and better interest rates than traditional banks. The philosophy behind a credit union is simple: members first. This approach is particularly evident in Denver, where credit unions have a strong community focus, offering personalized services that cater to local needs.

Key Characteristics:

  • Member-owned: Each member has a say in the union’s operations.
  • Non-profit: Excess earnings are returned to members through better rates and services.
  • Community-focused: Strong emphasis on local development and support.

The Growth of Credit Union Denver

In recent years, Denver has seen a significant rise in the popularity of credit unions. This growth is attributed to their ability to provide a more personalized banking experience and their commitment to serving the local community.

Innovative Solutions Offered by Denver Credit Unions

Personalized Financial Products

Customized Loan Options

Denver credit unions have gained recognition for their customized loan products, designed to fit the unique financial situations of their members. Whether it’s for a home, car, or personal loan, these institutions offer flexible terms and competitive rates.

  • Home Loans: Tailored mortgage options with favorable terms.
  • Auto Loans: Competitive rates for new and used vehicles.
  • Personal Loans: Flexible solutions for various personal needs.

Advanced Savings Accounts

Apart from traditional savings accounts, Denver credit unions offer various specialized accounts, like high-yield savings and accounts for specific goals like education or retirement.

Digital Banking Revolution

Online and Mobile Banking

Embracing technology, credit unions in Denver offer comprehensive online and mobile banking solutions. These platforms allow members to manage their accounts, pay bills, and access financial services remotely.

  • Mobile App Features: Includes mobile check deposit, real-time alerts, and more.
  • Online Financial Management Tools: Budgeting and tracking tools integrated into online banking.

Innovative Payment Solutions

Denver credit unions are also leading the way in offering modern payment solutions, such as contactless payments and digital wallets, catering to the needs of tech-savvy members.

Community-Driven Financial Education

Financial Literacy Programs

Understanding the importance of financial education, these institutions offer various programs and workshops aimed at enhancing the financial literacy of their members and the broader community.

  • Workshops and Seminars: Covering topics from budgeting to investment.
  • Online Resources: Providing accessible financial education materials.

Sustainable Banking Practices

Eco-Friendly Initiatives

In line with global trends, Denver’s credit unions are also adopting sustainable practices in their operations, contributing to environmental conservation.

The Future of Financial Solutions in Denver

As the financial world becomes increasingly complex, Denver’s credit unions are well-positioned to continue providing innovative and personalized financial solutions. Their commitment to their members and the community sets them apart, making them a crucial part of Denver’s financial ecosystem.

Looking Ahead: Trends and Predictions

  • Increased Adoption of Technology: Further advancements in digital banking and fintech collaborations.
  • Expansion of Customized Financial Products: More tailored solutions to meet specific member needs.
  • Greater Community Involvement: Enhanced focus on local development and support initiatives.

In conclusion, credit unions in Denver are reshaping the financial landscape with their innovative and member-centric solutions. From personalized financial products to digital banking revolutions, these institutions are not just keeping pace with the times but are setting new standards for what a financial institution can be. Their continued evolution and commitment to their members and community make “credit union Denver” a term synonymous with trust, reliability, and innovation in the financial sector.

It must be fun visiting different places you see on the internet. You can do it if you know how to get to the destination using public transportation. Renting a vehicle is also one of the options you have. But if you do not want to think of these two, consider buying and owning a car. Many people prefer this because of its convenience, especially if you travel daily. If budget is a hindrance to your plans, you can get a refinance car loan in Singapore.

4 THINGS TO REMEMBER BEFORE GETTING USED CAR LOANS IN SINGAPORE

A car can take you to many places, especially if you want to travel with your loved ones. However, some people have doubts about getting one because of financial restrictions. They might be paying more necessary matters, or their bills are not aligned. Whatever the reason is, check the complication, and you might do something about them. If you have decided and learned about used car loans in Singapore, you need to remember some reminders, like the following:

1. YOU NEED TO BE MORE RESPONSIBLE WITH YOUR MONEY BEFORE GETTING THE LOAN

If you will get a loan to get a car, remember to be more responsible with your money. Sacrifice something, especially for your wants. Think of your responsibility in paying the loan to avoid wasting your time and energy in getting it. It will also help you prevent issues with the loan company because they know you are paying on time.

2. SEARCH FOR A LEGITIMATE AND RELIABLE LOAN COMPANY

Before getting the car loan offer, search for a legitimate and reliable company. They will help you with correct in house used car financing and the pros and cons of getting it. You will see different companies on the internet, but you do not know if all of them are legal. Checking their company background and reading reviews will help you learn more about them and if they are the ones you need.

3. DO NOT FORGET TO CHECK THE AVAILABLE CAR MODELS

Before finalising your refinance car loan, do not forget to check the available car models based on your budget. It will help you know what you should choose, especially if you need something your entire family can use. But if there are issues with the money and the car model you want, think of another way to get the model or search for a more bearable vehicle you can buy.

4. YOU MUST FINALISE IF YOU WILL HAVE A BRAND NEW OR USED ONE

You can apply for a loan for your car, but you must finalise if you will purchase a brand new or second-hand one. It can affect the amount you will borrow from the loan company, especially if you are eyeing a brand-new car. You need to pay more for it, considering the quality and condition of the vehicle.

Here are the things you need to remember before getting a car to ensure you will not have problems with your loan. These can help you prepare for your monthly payment and budget your other expenses. Be responsible enough when getting loans to avoid having issues with the company. If you want to check a used car loan calculator in Singapore, visit the website of Swee Seng Credit.

With the advancement of technology, people have gained interest in the decentralization of currencies and their attempt to gain more transparency has resulted in the introduction of Bitcoins https://bitpapa.com. The most important feature of a cryptocurrency is that bitcoin price is not controlled by any governmental agency. It is theoretically immune to any governmental interference. You can easily buy and sell cryptocurrencies from trading platforms  where I can buy crypto in Nigeria.

What exactly is Bitcoin?

Cryptocurrency is a type of digital currency. It does not need the help of banks for its smooth running to confirm the transactions. It’s a peer-to-peer payment system. Its payments exist as digital inputs to an online database documenting specific transactions. Because it utilizes encryption to authenticate transactions, cryptocurrency got its moniker. This implies storing and sending bitcoin data between wallets. Encryption’s purpose is to ensure security and privacy.

Bitcoin is the most well-known cryptocurrency, having been launched in 2009. It was the world’s very first digital money. So, there’s a lot of interest. Therefore, the drive to benefit from trade has given rise to cryptocurrencies.

What is a crypto basic functioning principle?

The blockchain, a decentralized public database, is the foundation for crypto. So, this records all transactions of crypto. Mining is a process that necessitates the use of computers. In order to earn bitcoin units, you must complete challenging arithmetic problems. Brokers can also help users acquire currencies. Then, using encrypted wallets save and spend them. You are not having any tangible asset if you have crypto. What you have is the key. Therefore, it enables you to transfer a record or a unit of measurement from one person to another without the assistance of a reliable third party.

Despite the fact that Bitcoin has been around since 2009, crypto and blockchain technology at present is still underdeveloped. It is still at its early stage.

Examples of digital currency

There are tens of thousands of different cryptocurrencies to choose from. Here’s the list of popular crypto

Bitcoin cryptocurrency:

Bitcoin created in 2009 and is today the most traded cryptocurrency. It was the first crypto. Satoshi Nakamoto is a pseudonym for someone or group of people. Whose exact identity is unknown, created the currency.

Ethereum cryptocurrency:

Ethereum is a cryptocurrency that runs on blockchain technology. ETH is a cryptocurrency and introduced in 2015. So, after bitcoin ETH is the most popular crypto.

Litecoin cryptocurrency:

This currency is the most similar to bitcoin. It has, however, moved rapidly to create new technologies, such as faster payment processing. And mechanisms that make it possible to do additional transactions.

Ripple cryptocurrency:

Ripple is a distributed ledger platform based on the blockchain that was developed in 2012. However, be used to track a variety of other transactions. So, its founders have worked with a variety of businesses.

When it comes to presenting an overall picture of Bitcoins, it can be clearly stated that Bitcoins are the future when it comes to developed countries, but several new features are needed to be introduced to make it a safer currency.

To get larger cash, now you can strive to enjoy shares via exceptional inventory brokers. Investments and different things to do in the inventory market are being linked with the aid of the public due to the fact they are viewed as secure and profitable.

Even so, you cannot simply select the Stock Broker you will use. There are various symptoms that ought to be viewed so that inventory funding things to do stay cozy to use. Choosing Stock Broker can no longer be arbitrary.

Online Trading

Transacting the usage of online trading capacity that you region a purchase and promote order yourself, barring the assistance of a broker, via the usage of an online buying and selling software supplied by using securities.

The requirement to be in a position to do online trading is the existence of a web network. Currently, there are many securities that furnish online buying and selling offerings that can be accessed both via a computer, tab, or smartphone.

The gain of the use of an online trading device is that it saves time in conducting transaction activities.

If you enter purchase and promote the order yourself, it is quicker than calling a broker. In addition, with online trading, the rate charged is smaller due to the fact there is no want to pay a broker.

The drawback when the usage of an online trading device is the hazard if the net is no longer linked properly. Especially if you are a momentary dealer who is required to display shares to acquire momentum.

How many brokers provide online trading facilities? It is advocated that you select software that is stable, comfortable, and effortless for you to use, beginning from the display, connections that do not drop out often, and others.

Every online trading is commonly downloaded from the web and can be tried even if you are now not a client of the broker.

how to invest in stocks

Even although it is on the rise, some human beings are afraid to begin investing in stocks. In fact, how to begin investing in shares for novices is now not too difficult, as long as you have a sturdy will and determination, and enough knowledge.

Allocate Time to Study

Of course, if we favor being concerned about something, it is better for us to extend our expertise about it, and inventory funding is no exception. The first step earlier than you begin buying and selling stocks, take the time to analyze the ins and outs of shares first. Learn the fundamentals of inventory investing, recognize the phrases that are regularly used, and additionally hone your competencies by means of the usage of various buying and selling debts furnished for buying and selling simulations in the inventory market.

Choose the Right and Guaranteed Broker

Well, after you deepen your understanding of stocks, the subsequent step is to learn about inventory brokers. It is very necessary to be aware of what brokers there are due to the fact there are many of them. You need to no longer simply pick a broker or securities, due to the fact every one of them has one-of-a-kind transaction fees for shopping for and promoting shares. The lower the cost, the greater you can benefit. But it is now not always a safe enterprise that applies excessive fees is continually awful due to the fact the provider might also be higher and the utility extra satisfying. Choose the proper securities in accordance with what you want and are assumed to be proper by means of searching at the on-hand song records.

Get to be aware of the organization and the industry

Next, find out about and analyze the situation of the company. Such as discovering the heritage and movements of the organization in enterprise development. For example, has the organization usually made a profit, or has it been misplaced in the final few years? Also reflect on consideration on exterior elements that can have an effect on the price of the company’s shares later, such as socio-political problems that can motivate the shares to fall easily.

Do no longer supply up easily

The key to the success of investing in shares is consistency and patience. Always optimistic, in no way giving up, and now not being afraid to take risks will make you better at conserving inventory investments for profit. Don’t be afraid of the chance of failure or choose to get wealthy quickly, constantly instill that mindset earlier than you even start. A person’s success is influenced by using the attitude due to the fact it has a large impact.